Mortgage Agent Level 1 · Sarnia, Ontario
Mortgagesmade easier.
Clear advice. Better understanding. Confident decisions.
I teach elementary school for a living. This is the same job with a different subject.
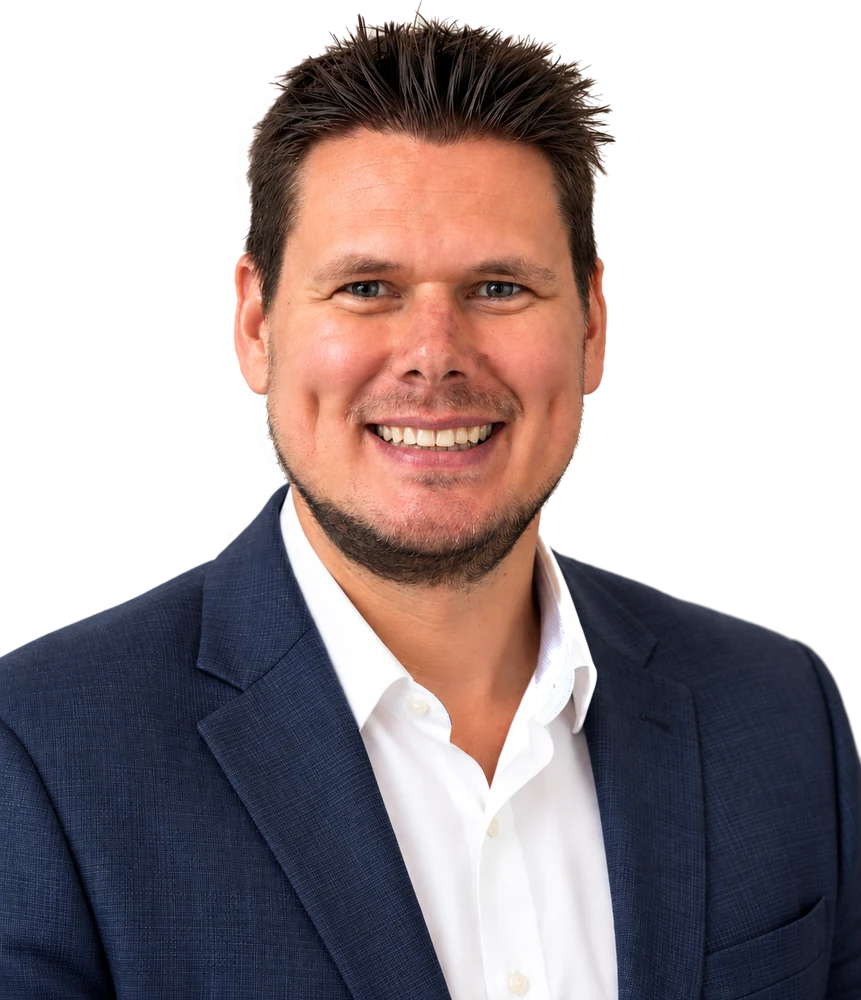
Darrell Robertson
Mortgage Agent Level 1
Tango Financial (ON) Mortgage Corporation
Licence #13691
Margin note
Based in Sarnia, licensed across Ontario. Classroom teacher by day, mortgage agent since September 2026.
Meet Darrell
I explain thingsfor a living.
I teach elementary school. Most days that means taking something genuinely complicated and finding the version of it a nine-year-old can hold onto. Turns out that's a useful habit to bring to a mortgage.
My wife sells real estate, so I've had a front-row seat to how these deals actually come together, and to how often people sign the biggest document of their life without anyone walking them through it properly. That's the gap I wanted to fill.
Plain language
If I use a term you haven't met before, I stop and explain it. Nobody should sign something they can't describe out loud.
The whole picture
Rate matters. So do the prepayment terms, the penalty if you break it early, and whether the payment still works if life changes.
No pressure
I'd rather you walk away understanding your options than commit to something because you felt rushed.
What I do
Six ways peopleend up here.
Find the one that sounds like you. Each starts the same way: a conversation where you get to ask the obvious questions.
How it works
Four steps.No mystery.
You should always know where your file is and what happens next. If you ever have to chase me for that, I've done it wrong.
- 01
A conversation first
Twenty minutes, no forms. You tell me what you're trying to do, I tell you what stands between you and it.
- 02
The application
I send you a secure link. You fill in what you can, and I chase the rest. Nothing goes to a lender until you've seen it.
- 03
Options, explained
I come back with what is available and what each option really means for your monthly payment and your flexibility. In plain English, in writing.
- 04
Through to close
Conditions, lawyer, funding date. I stay on it and tell you what's happening before you have to ask.
Run the numbers
Play with itbefore you worry.
Move the sliders. Watch what a half point does, or what another five percent down changes. Getting a feel for the shape of it is most of the work.
Estimated monthly payment
$2,602
- Mortgage amount
- $472,500
- Down payment
- $52,500
- Interest over 25 years
- $308,113
Of everything you would pay over 25 years,39%is interest. Shortening the amortisation or paying down the principal early moves that number.
Under 20% down, mortgage default insurance applies and gets added to the mortgage. This estimate doesn't include it.
An estimate, not an approval or a rate quote. It leaves out property tax, heat, condo fees and closing costs, and assumes semi-annual compounding on a fixed rate.
The lender network
One conversation.More than one door.
I'm licensed with Tango Financial (ON) Mortgage Corporation. Your file isn't limited to whatever one bank happens to be offering this month.
Which lenders actually fit depends on your income, your credit and the property. Working that out is the job. I'll tell you who I'm submitting to and why before anything goes anywhere.
Chartered banks
The names you already know
Credit unions
Often more flexible on the unusual file
Monoline lenders
Mortgage only, and competitive for it
Alternative lenders
For income that doesn't fit a box
Private lenders
Short term, specific situations
The obvious questions
Ask them.All of them.
There is no such thing as a question you should already know the answer to. Here are the ones that come up most.
It depends on income, existing debts, the down payment, the rate and the property costs, and the honest answer is that the maximum a lender will approve isn't always the number you should use. We work out both: what you qualify for, and what leaves you room to live.
It means a lender has looked at your income and credit and indicated what they would likely lend, usually with a rate held for 90 to 120 days. It is not a guarantee. The property still has to pass, and your situation still has to look the same at closing as it did on the application.
Fixed buys you certainty and costs a premium for it. Variable moves with the prime rate, which can go either way. The right answer depends on how much payment change you could absorb without losing sleep, and how likely you are to break the mortgage early. I won't tell you one is objectively better, because it isn't.
Usually recent pay stubs, a letter of employment, two years of tax documents, and statements for your down payment showing where it came from. Self-employed files need a bit more. I'll send you a specific list rather than a generic one.
No. Your own bank can only offer you their own products. Going through a brokerage means your file can be placed with whichever lender fits it best, which sometimes is your bank and often isn't.
On a typical residential mortgage the lender pays the brokerage, so there is no fee to you. Some files, usually alternative or private lending, do carry a fee. If yours is one of them I'll tell you the number before we go any further, not at the end.
Ready when you are
Let’s make your nextmove make sense.
Twenty minutes on a call costs you nothing and usually answers more than an evening of reading. Bring your questions.
Guides for each of the six paths are being written. Want one before it's finished? Ask me on the call and I'll send you what I have.